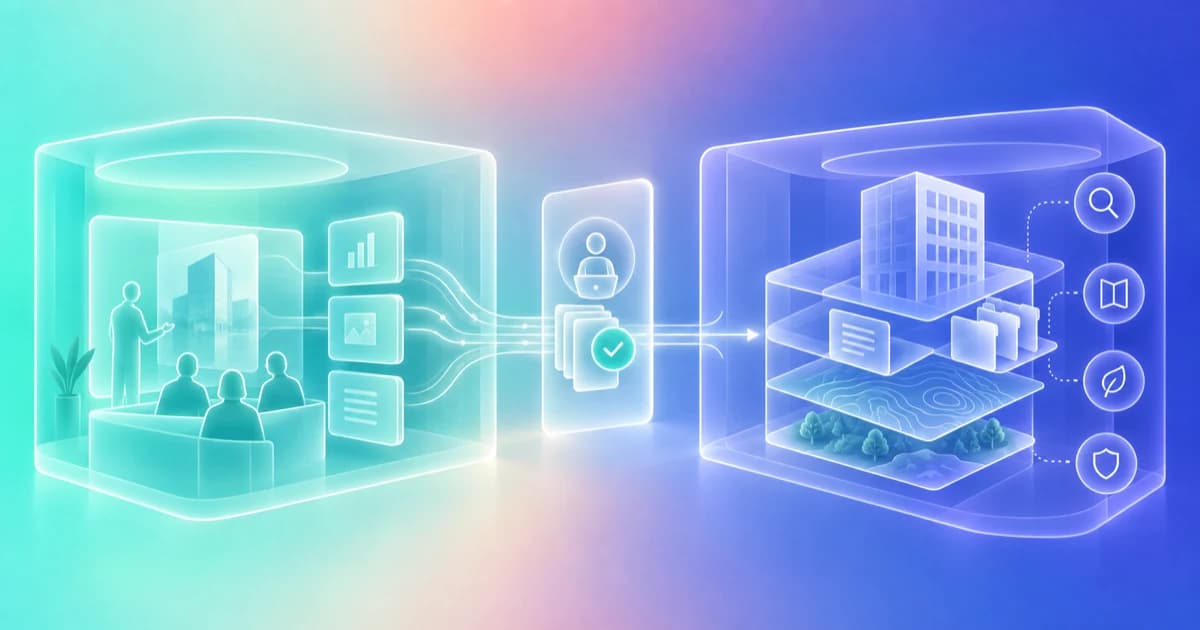
Real estate fundraising and property diligence need separate rooms
A real estate data room should not mix two different decisions. Prospective investors need to evaluate the sponsor, offering, and capital plan. Buyers, lenders, counsel, and technical advisers may need to evaluate the property itself. Separate those rooms, then connect them with a clear index and responsible owners.
This two-room model reduces accidental oversharing and makes unanswered questions visible. It does not determine which documents a particular offering or transaction legally requires.
Room 1: sponsor and fundraising diligence
The fundraising room explains why the sponsor is raising capital and how the proposed investment is structured. Common sections include:
- approved sponsor and team overview;
- relevant track-record support with clear attribution and methodology;
- investment thesis and business plan;
- offering summary and current approved materials;
- sources and uses of funds;
- capitalization, debt, and reserve assumptions;
- fees, promote, conflicts, governance, and decision rights as stated in approved documents;
- material risks and sensitivities;
- current fundraising status stated without turning indications into commitments;
- counsel-approved execution materials shared through the designated process.
The sponsor should identify which statements are historical facts, third-party reports, current estimates, or forward-looking assumptions. A polished room does not make projections certain.
Room 2: property diligence
The property room supports review of the asset, operations, title, physical condition, and financing. Depending on the property and transaction, the room may include:
- property description and unit or space schedule;
- rent roll and lease support;
- historical operating statements and current budget;
- appraisal and valuation support;
- title, survey, zoning, easement, and land-use materials;
- property-condition, inspection, engineering, environmental, or seismic reports;
- insurance coverage and claims information;
- capital expenditure history and planned work;
- material vendor, management, or service agreements;
- tax information and assessments;
- debt terms, lender requests, and closing items;
- open issues, remediation plans, and updated third-party reports.
Freddie Mac's current multifamily underwriting checklist, for example, calls for property-specific items including insurance, management information, zoning, inspection documentation, rent rolls, and historical property financial statements in relevant underwriting packages. Fannie Mae's Multifamily Guide separately covers valuation, income, legal compliance, inspections, insurance, environmental information, leases, and property-condition review.
Those sources illustrate the breadth of property diligence. They are not a checklist for every private real estate raise or transaction.
Why the separation matters
| Question | Fundraising room owner | Property room owner |
|---|---|---|
| Who is the sponsor and what is the strategy? | GP, sponsor, or investor-relations lead | Referenced only as needed |
| What security or fund interest is being offered? | Sponsor and counsel | Not answered by the property files alone |
| What is the capital plan? | Sponsor and finance lead | Property assumptions provide support |
| What is the current rent and expense evidence? | Summarized in approved fundraising material | Property finance and asset-management source files |
| What physical or environmental issues exist? | Material implications disclosed appropriately | Third-party reports and remediation records |
| What access should a prospective LP receive? | Fundraising owner applies stage and identity rules | Sensitive property files are released only when needed |
| What happens after close? | Moves to the designated investor-service and administration process | Moves to asset-management, lender, and transaction systems |
One file can support both decisions, but it should still have a clear source owner, status, date, and access policy.
A four-stage disclosure model
1. Initial sponsor review
Share the approved investment summary, sponsor information, high-level business plan, capital need, and next step. Avoid sending a complete property archive before the recipient has established fit and interest in reviewing the opportunity.
2. Qualified investor review
Open the detailed underwriting summary, property financials, material assumptions, and key third-party reports appropriate to the conversation. Confirm recipient identity and any required confidentiality process.
3. Active diligence
Provide deeper property, legal, financing, operating, and risk support as requests become specific. Assign each request to an owner and record whether the answer is present, missing, unverified, or not applicable.
4. Subscription and closing
Move identities, signatures, subscription documents, payments, and official closing records through the approved legal, banking, and administration systems. A fundraising room should not be presented as a substitute for those systems.
If the offering relies on a specific securities-law exemption, the sponsor and counsel must determine the applicable process. The SEC notes that Rule 506(b) and Rule 506(c) impose different standards for assessing accredited-investor status. A software accreditation field does not make that determination for the issuer.
A synthetic example
Harbor Block Partners is raising $8 million of equity for a 120-unit multifamily acquisition. The facts below are illustrative.
Fundraising room
The sponsor shares:
- an approved overview of the property and business plan;
- the sponsor team and attributable history;
- a sources-and-uses schedule;
- return scenarios labeled as assumptions rather than promises;
- an explanation of fees, promote, debt, reserves, and conflicts from approved materials;
- the current offering and risk materials prepared with counsel;
- a clear path for questions and next steps.
Property room
After a prospective investor enters active diligence, the sponsor releases:
- the current rent roll and trailing operating statements;
- selected lease support;
- the inspection and property-condition materials received to date;
- title, survey, zoning, environmental, insurance, tax, and debt materials where applicable;
- the capital-expenditure plan and open remediation items;
- a request tracker showing owners and dates.
The team does not describe a third-party report as verified simply because it has been uploaded. The index records its author, report date, recipient, and any unresolved follow-up.
Build the index before the room
Use the data room due diligence checklist as the canonical document-list resource, then adapt it to the property and offering. The index should include:
| Field | Why it matters |
|---|---|
| Document or request | Names the expected evidence |
| Room | Separates sponsor fundraising from property diligence |
| Source owner | Identifies who can verify the answer |
| As-of date | Shows whether the information is current |
| Status | Present, missing, unverified, or not applicable |
| Access stage | Initial, qualified, diligence, or closing |
| Sensitivity | Helps determine whether to redact, restrict, or withhold |
| Notes and limitations | Preserves what the file does not establish |
Run the data room completeness workflow against the index instead of asking whether the folder looks full.
Security and privacy boundaries
Real estate rooms can contain personal information, tenant records, banking details, wire instructions, confidential leases, and technical reports. Minimize what is collected and shared. Limit access to people with a business need. Confirm the designated system for signatures, identities, payments, and regulated data.
Access controls do not prevent every screenshot or downloaded copy. Review the secure investor document-sharing guide before opening the room.
What Finta can support
Finta Documents can organize uploaded files and folder hierarchies and make supported indexed formats available to Aurora. Finta Share Pages can present approved materials with public, email-required, or email-verified access. Supported identified session activity can return to the relevant relationship record.
Finta can help a sponsor connect investor targets, relationship context, fundraising materials, questions, and reviewed follow-through. It does not validate the property, verify projections, provide market data, make investment recommendations, determine securities-law compliance, administer the vehicle, process subscriptions, perform KYC/AML, execute payments, or replace counsel, accountants, lenders, engineers, environmental advisers, or fund administrators.
Use the real estate fundraising solution to coordinate the capital-raising relationship while keeping property facts and official records in the systems responsible for them.
Sources and review notes
- Freddie Mac Multifamily conventional underwriting checklist, reviewed September 14, 2026
- Fannie Mae Multifamily Guide, reviewed September 14, 2026
- Fannie Mae lease audits, inspections, and reserves, reviewed September 14, 2026
- SEC guidance on assessing accredited investors under Regulation D, reviewed September 14, 2026
- FTC, Start with Security, reviewed September 14, 2026
- Finta Share Pages, reviewed September 14, 2026
- Finta Documents, reviewed September 14, 2026
This article provides general operating guidance. It is not legal, investment, tax, accounting, security, lending, engineering, environmental, valuation, or compliance advice.